Skip to content

Buying a home
as a doctor?
Start here.

A free, comprehensive guide to mortgage types, debt-to-income ratios, down payments, prequalification, and more, written for physicians, dentists, and vets preparing to buy a home. 

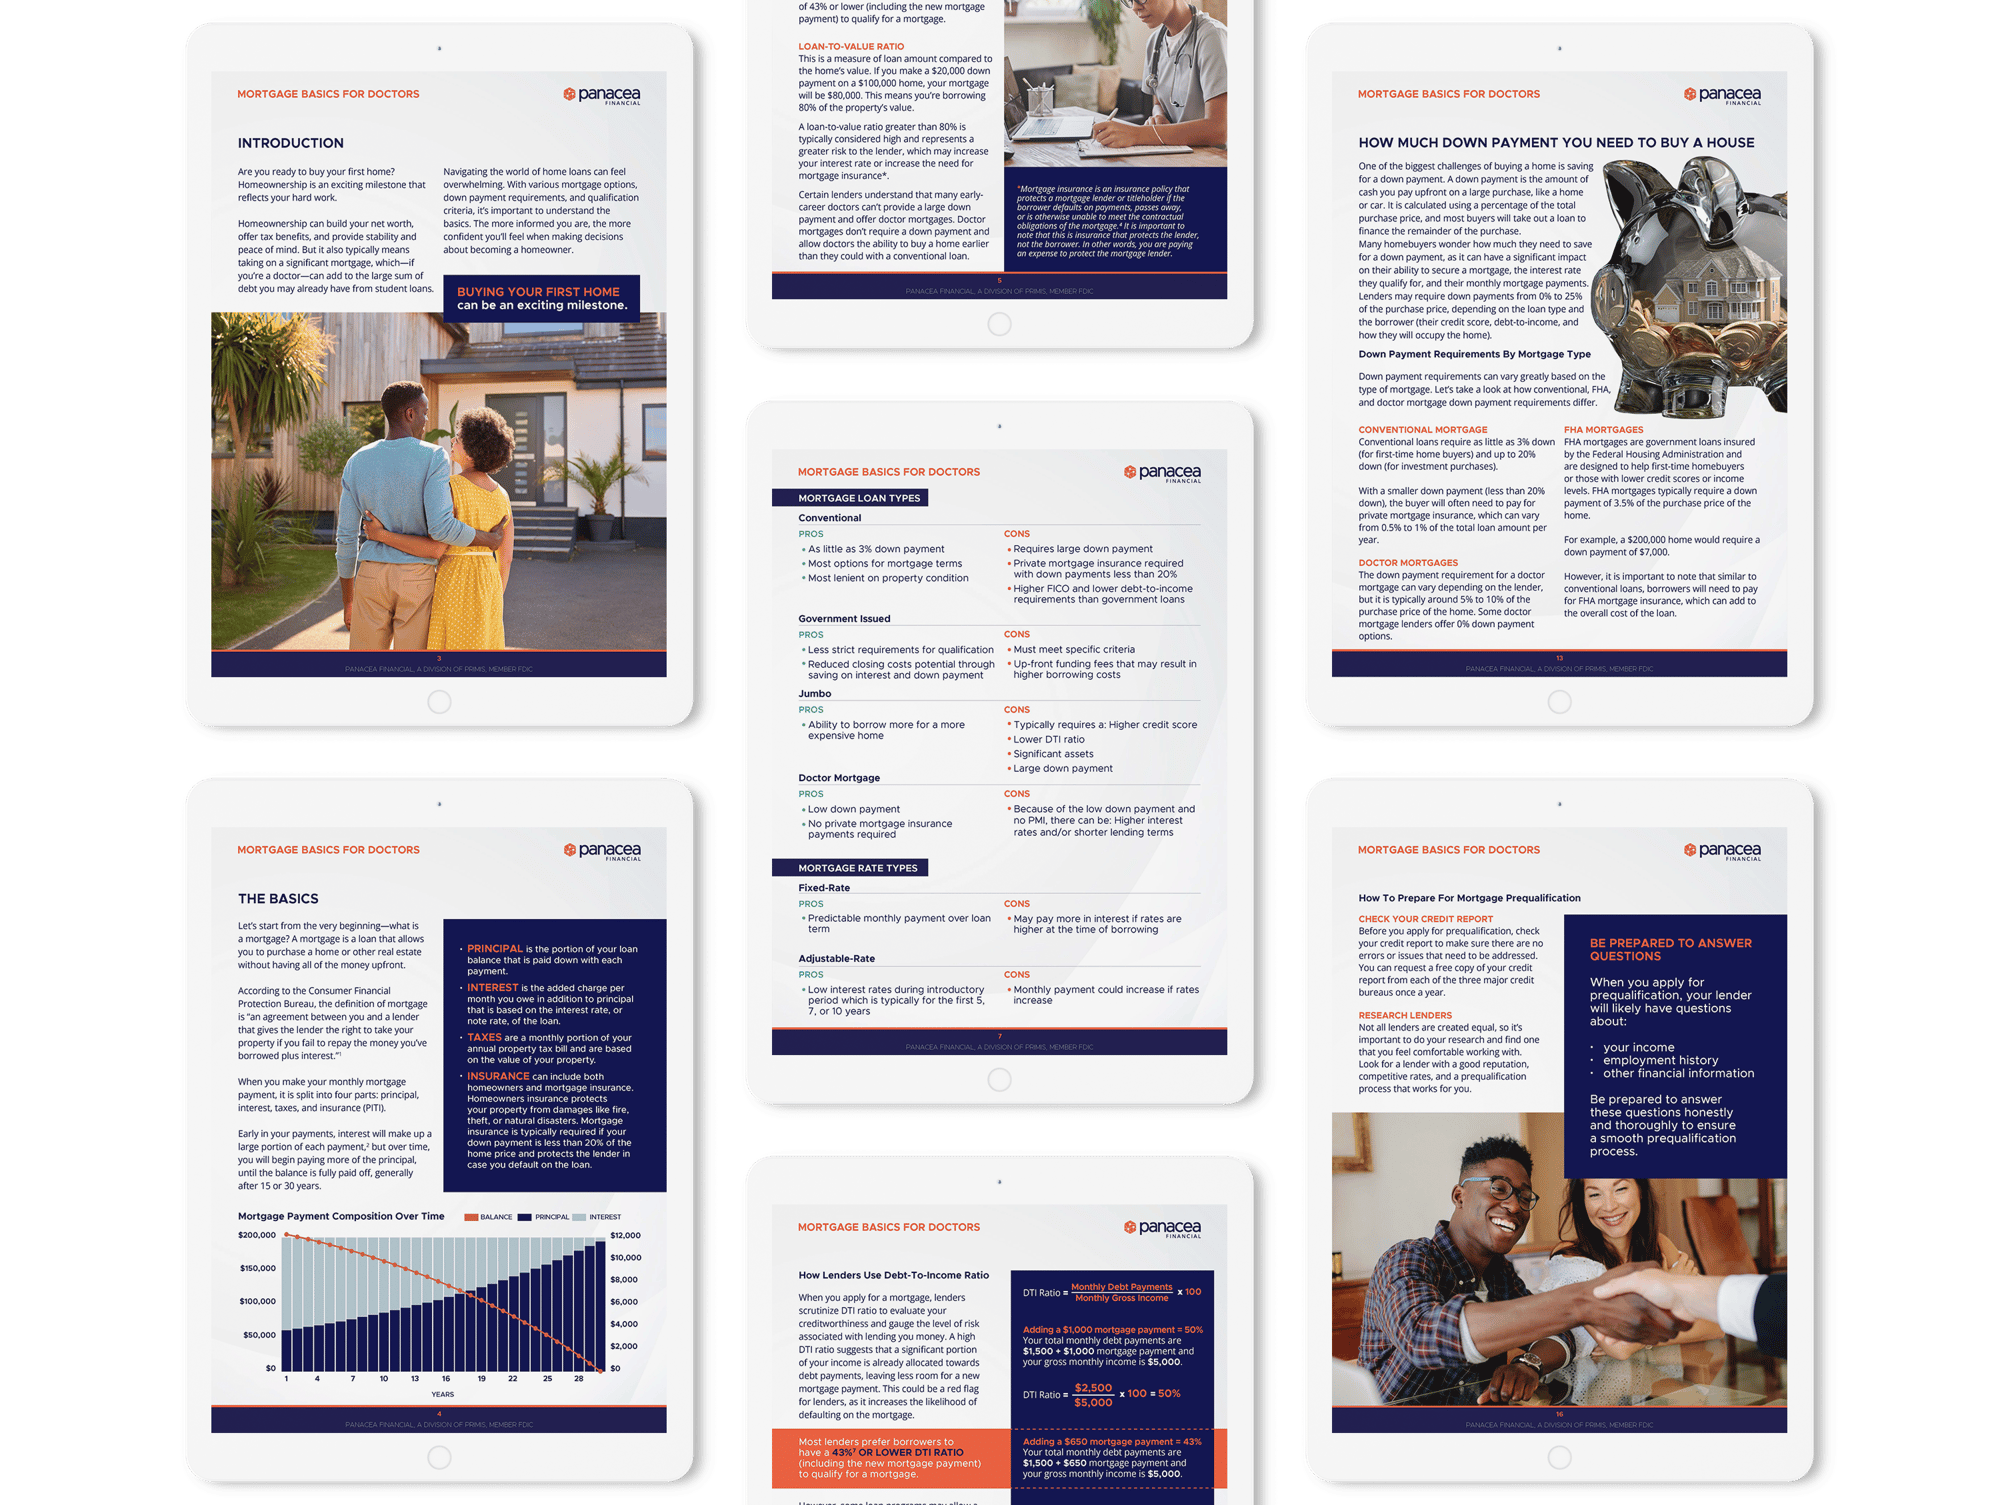
Mortgage Tablet screens

A Doctor’s Path To Homeownership Isn’t Standard


Student loans, delayed income, and an unusual debt-to-income picture may change how you approach buying a home, but they don’t have to stay in your way. In fact, 59% of physicians surveyed by Medscape are already paying down a mortgage on their primary residence.1

This guide shows you how to get there on terms built for your career.

1. Medscape


Download Today

What
The Guide
Covers

Interest Rates

Understand how mortgage rates are determined and what borrowers can do to improve their rate.

Mortgage Types

Identify the different types of mortgages available to borrowers and when it makes sense to use each type.

Doctor Mortgages

How doctor mortgage programs are designed to accommodate student loans and little or no down payment.

Debt-to-Income

Learn how debt-to-income ratio influences mortgage approval and how to calculate your own.

Down Payments

See how mortgage type changes down payment requirements and learn the benefits and drawbacks of making a large down payment.

Prequalification

Understand how prequalification helps the homebuying process and the steps to get prequalified.

Questions To Ask

Access a list of 10 questions to ask your lender before you secure your mortgage.

Built For Every Stage Of Your Career


Whether you're years from buying or ready to make an offer, this guide meets medical, dental, and veterinary professionals where they are. Here's what you'll take away at your stage.

Students

Build a foundation of mortgage knowledge now, so you’re ready to move with confidence when the time comes to buy your first home.

Residents & Fellows

Understand the terms, timelines, and decisions ahead, so you can prepare to buy your first home without surprises.

Practicing Doctors

Get a clear walkthrough of mortgage types, debt-to-income, down payments, and prequalification so you can buy your first or next home with confidence.

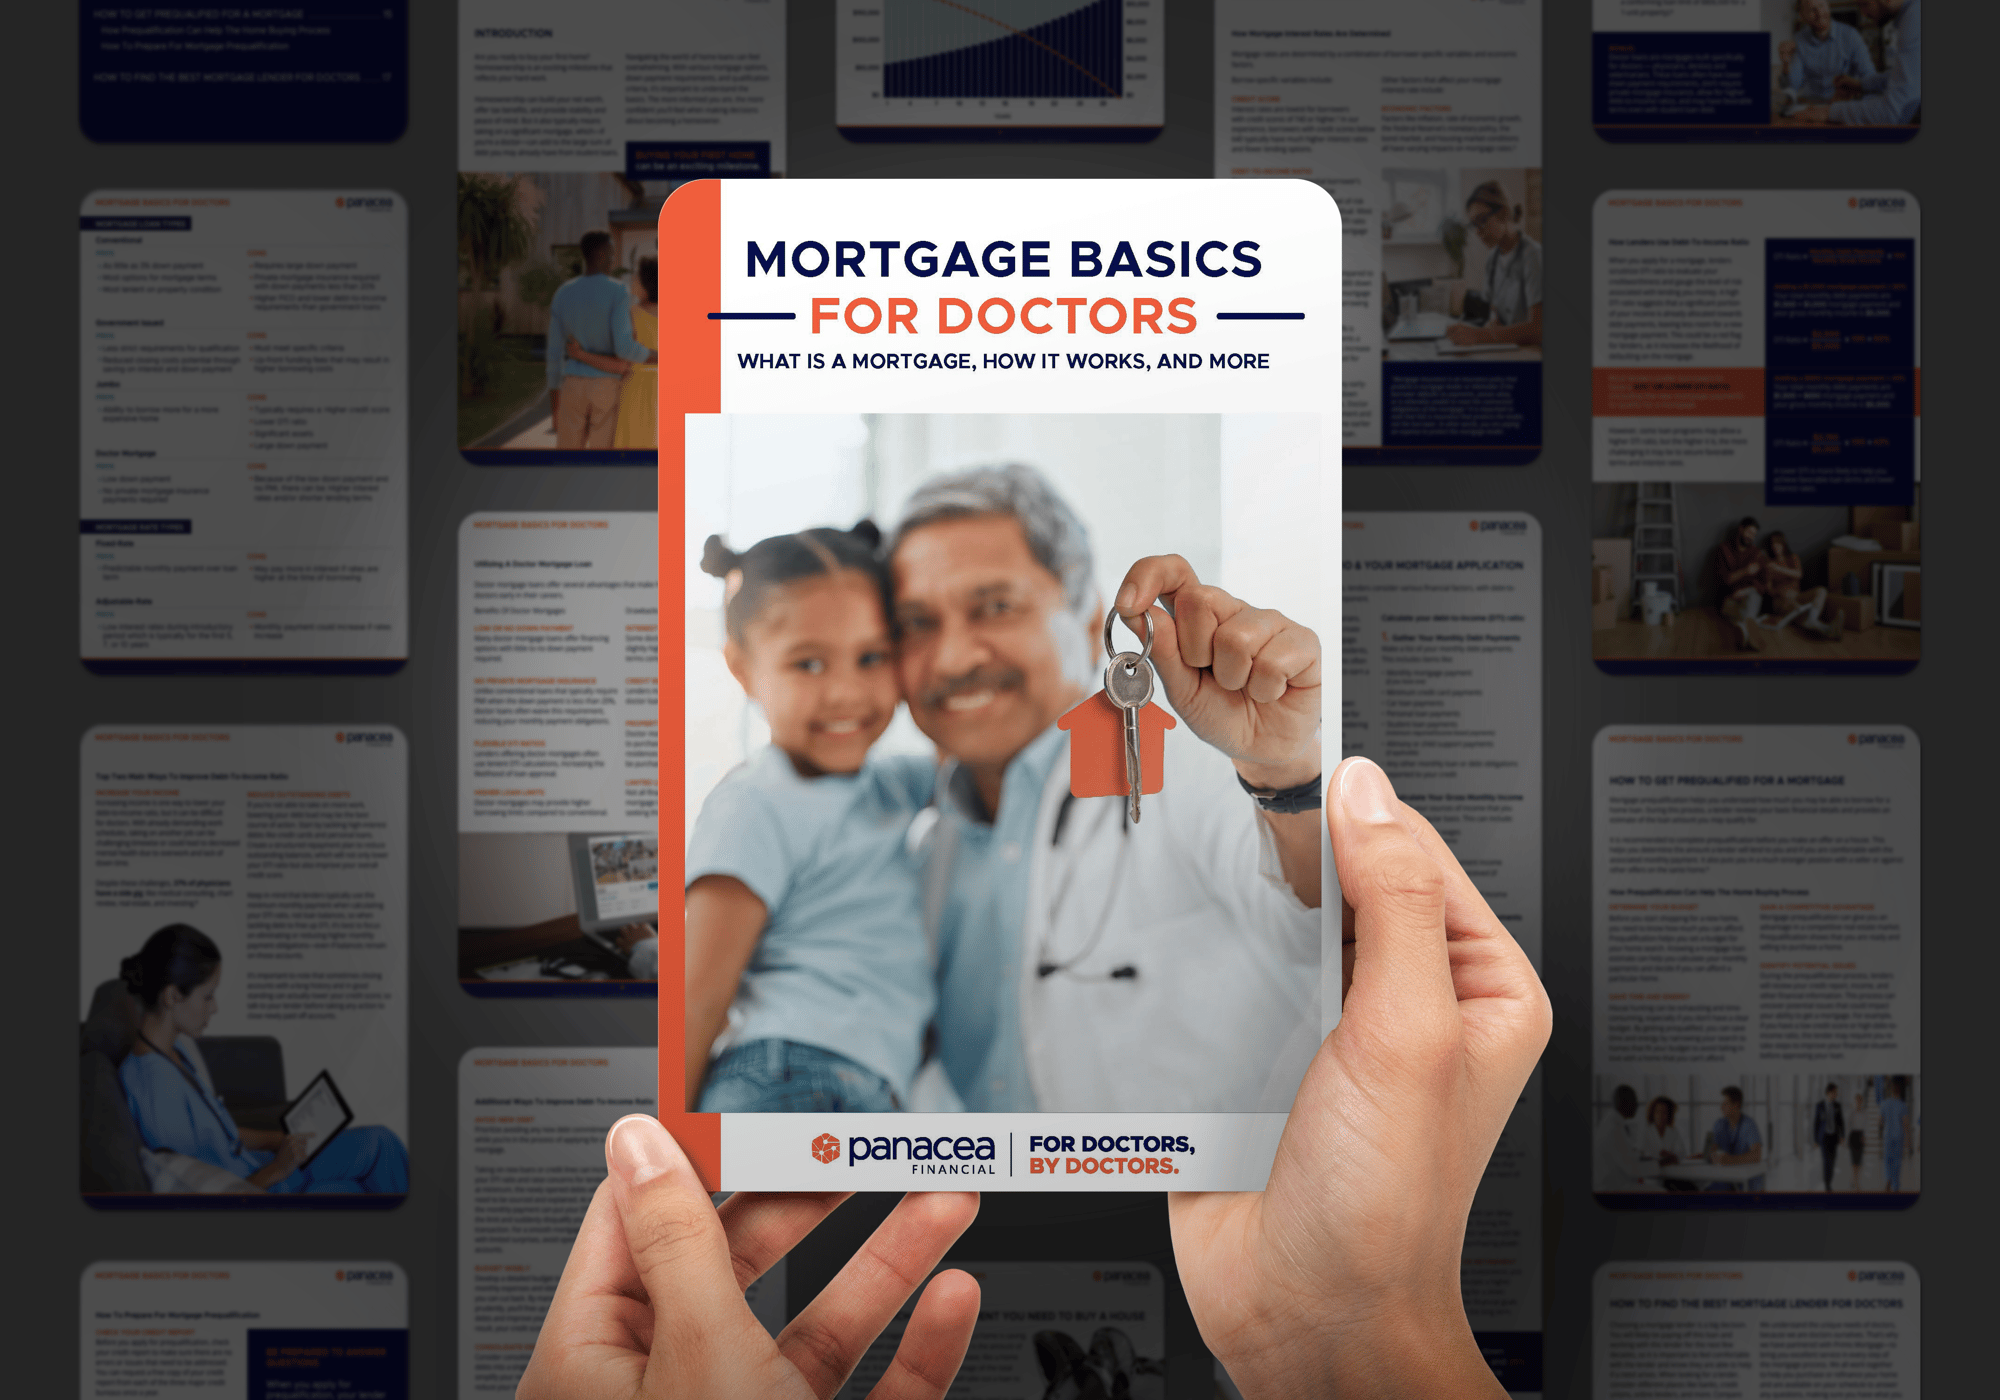
Mortgage Ebook

About the Authors

Michael-3 (1)

Michael Jerkins, MD, M.Ed

President & Co-Founder, Panacea Financial

Michael is the President and Co-founder of Panacea Financial and is also a practicing physician in Little Rock, AR. He built Panacea to solve the financial problems he and his peers ran into through school, training, and practice.

Daryl-Summer,  Summer 2024

Daryl McCarthy

Loan Officer (NMLS#: 39582), Primis Mortgage

Daryl McCarthy is a Loan Officer with Primis Mortgage, a partner of Panacea Financial. With over 25 years of experience in the mortgage industry and a passion for assisting families in realizing their dreams of home ownership, Daryl brings dedication and expertise to his role. 

FAQs

Mortgage rates are determined by a number of factors based on both the individual borrower and the economy at the time of lending. Factors that are based on the borrower include credit score, debt-to-income ratio, and loan-to-value ratio.
The three most common types of mortgages are conventional, government, and jumbo. These loans may be fixed-rate or adjustable-rate. Doctors may also be eligible for doctor mortgages, which are built specifically for the unique financial circumstances of physicians, dentists, and veterinarians.

Debt-to-income (DTI) ratio is the percentage of your monthly gross income that goes toward debt payments. Lenders use DTI ratio to evaluate your creditworthiness and gauge the level of risk associated with lending you money.

Down payment requirements vary by type of mortgage. Conventional loans require as little as 3% down. Doctor mortgages may offer 0% down payment options.

Prequalification can help you determine how much you can comfortably afford, give you a competitive advantage in the real estate market, save time and energy when searching for the right home, and identify any potential issues that could impact your ability to get a mortgage.

Disclosures

Panacea Financial is a division of Primis Bank. Member FDIC.

This content is for educational purposes only and is not legal, tax, or financial advice.

The information and advertised terms, including interest rates, are from Primis Mortgage Company (www.nmlsconsumeraccess.org NMLS# 1894879; Equal Housing Lender). Mortgage applications can only be submitted in those states that Primis Mortgage is approved to lend. Panacea Financial is not a mortgage lender in any transaction and does not make mortgage loans, mortgage loan commitments or lock-rates related to mortgage loans. All credit decisions for mortgage loans, including loan approval and the conditional rates and terms offered, are the responsibility of Primis Mortgage Company and will vary based upon the loan requested, program guidelines, the borrower’s financial situation, and criteria determined by Primis Mortgage Company. Not all consumers will qualify for the advertised rates and terms. All information provided is subject to verification. Other terms and conditions may apply. Panacea Financial does not guarantee that Primis Mortgage Company will make you a conditional loan offer and nothing herein or on this website is considered a commitment to lend. Panacea Financial is a division of Primis Bank and Primis Mortgage Company is a subsidiary of Primis Bank.